NCC BULGARIA

NCC presenting the success story:

NCC Bulgaria is the National Competence Centre for HPC and HPDA, operating within the EuroCC3 network and EuroHPC ecosystem. Coordinated by the Institute of Information and Communication Technologies at the Bulgarian Academy of Sciences (IICT-BAS) in partnership with the Sofia University “St. Kliment Ohridski” (SU) and the University of National and World Economy (UNWE), it supports industry, academia, and public organizations through specialized training, consulting, technical expertise, and access to national and European HPC resources.

Scientific partners involved

The Institute of Information and Communication Technologies (IICT-BAS) conducts fundamental and applied scientific research in the fields of high-performance computing (HPC), machine learning, big data processing, cybersecurity, optimization, financial modeling and mathematical modeling. The developed methods and technologies find application in medicine, ecology, industry, transport, financial analysis, process optimization, and digital transformation.

Technical/scientific Challenge

Constructing reliable investment portfolios requires balancing expected returns, market volatility, and potential losses under adverse market conditions. For a diversified universe of 32 global financial assets, the large number of possible allocations makes constrained portfolio optimization computationally demanding. An additional challenge is that different risk measures, such as the Sharpe ratio and Conditional Value-at-Risk (CVaR), may favour substantially different investment strategies. Portfolio decisions are also sensitive to the historical estimation period and the numerical sampling method. The research therefore investigates how Monte Carlo (MC) and randomized Quasi-Monte Carlo (QMC) algorithms can efficiently identify feasible portfolios while assessing numerical accuracy, computational cost, and sensitivity to market conditions.
Solution

Researchers at the Institute of Information and Communication Technologies of the Bulgarian Academy of Sciences (IICT-BAS) developed a reproducible Python-based framework for stochastic portfolio optimization using the HEMUS supercomputer. The methodology compares classical Monte Carlo sampling with Mersenne Twister and randomized Quasi-Monte Carlo methods based on scrambled Sobol and randomized Halton sequences. Candidate portfolios are generated under full-investment and long-only constraints, with a maximum allocation of 30% per asset. We investigate two optimization objectives: maximizing the Sharpe ratio to improve risk-adjusted returns and minimizing historical CVaR to limit losses in the worst 5% of monthly observations. The analysis considers three historical estimation windows of 3, 5, and 10 years and five candidate budgets ranging from 128 to 2048. We evaluate each configuration through 50 independent randomized repetitions and compare it with deterministic numerical benchmarks using approximation errors, portfolio characteristics, and execution times. This computational framework enables systematic analysis of how sampling techniques, risk objectives and historical periods influence portfolio selection.

Scientific impact

Methodology and Computational Framework

The research presents a reproducible Python-based framework for stochastic portfolio optimization, implemented on the HEMUS supercomputer at IICT-BAS. The study examines 32 global financial assets across 3-, 5- and 10-year historical windows, comparing Monte Carlo (with pseudorandom generator Mersenne Twister) and randomized Quasi-Monte Carlo (with scrambled Sobol and Halton) methods under Sharpe ratio maximization and CVaR minimization.

  • Experiment 1 – Accuracy and Convergence of Stochastic Portfolio Search: Five sampling budgets (128–2048 candidate portfolios) and 50 independent repetitions per configuration were evaluated against deterministic numerical benchmarks. Increasing the number of candidates reduced approximation errors, while differences between sampling methods remained modest, with classical Monte Carlo generally requiring less execution time.
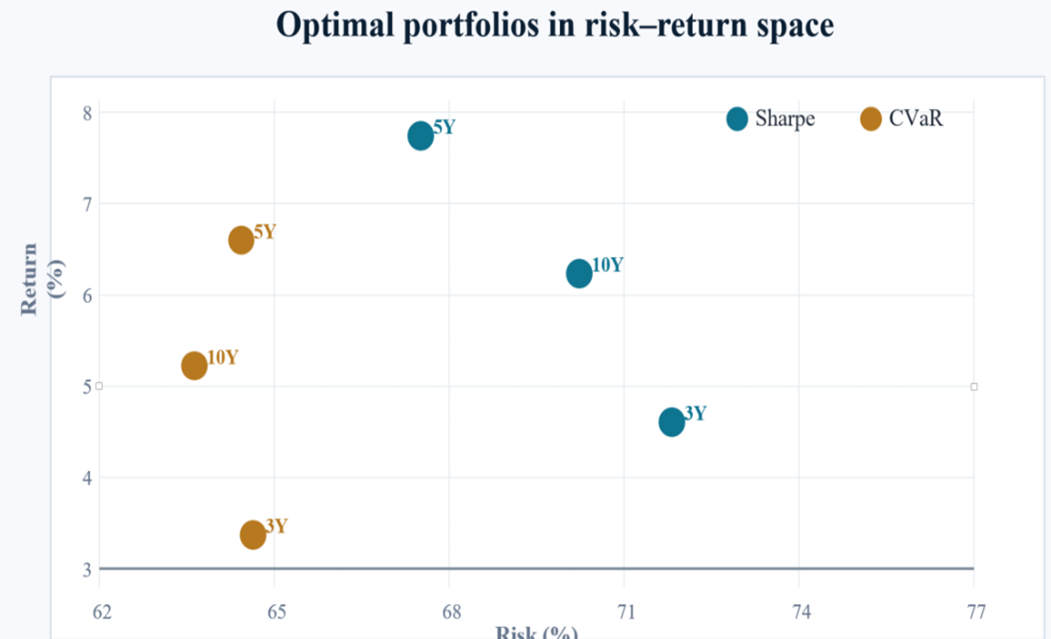
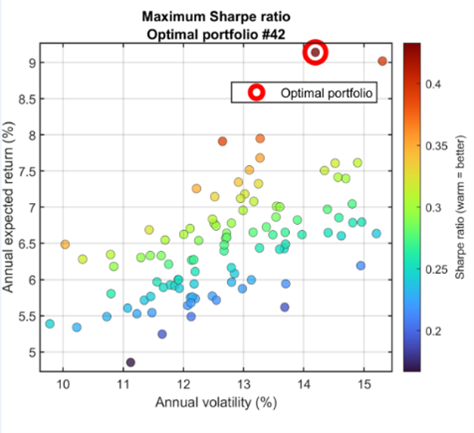
  • Experiment 2 – Financial Risk – Return Comparison: The 5-year Sharpe-oriented portfolios achieved a mean annualized return of 9.15%, while the 10-year CVaR-oriented portfolios recorded the lowest mean historical monthly CVaR of 4.40% and annualized volatility of 6.59%. These results highlight the trade-off between maximizing risk-adjusted returns and minimizing downside risk.
  • Experiment 3 – Historical Window and Sampling Sensitivity: The 3-, 5- and 10-year estimation windows produced different portfolio allocations and risk–return characteristics. The optimization objective and historical period generally had a greater influence on portfolio selection than the choice of sampling generator.

Scientific Contribution

The study demonstrates the potential of HPC-supported stochastic optimization for reproducible financial risk analysis and numerical benchmarking. The HEMUS supercomputer enabled extensive computational experiments, providing a foundation for scalable portfolio optimization and future financial decision-support systems.

Benefits: 

  • Improved optimization accuracy: Larger sampling budgets reduce approximation errors relative to deterministic benchmarks.
  • Risk-aware portfolio selection: Compares return-oriented Sharpe optimization with downside-risk-focused CVaR.
  • Reliable numerical benchmarking: Evaluates accuracy, stability and computational efficiency across MC/RQMC methods.
  • Better understanding of market sensitivity: Reveals how historical estimation windows influence investment outcomes.
  • HPC-enabled research: Supports repeated simulations and scalable numerical experimentation.
  • Future financial applications: Provides a foundation for computational portfolio analysis and investment decision-support systems.

Success story # Highlights:

  • Keywords: HPC; Monte Carlo; Quasi-Monte Carlo; Portfolio Optimization; Sharpe Ratio; CVaR; Financial Risk.
  • Technology: HEMUS Supercomputer; Python; Mersenne Twister; Scrambled Sobol and Halton; Stochastic Optimization.
  • Industry sectors: Finance/Insurance; IT/HPC Systems, Services & Software Providers.
  • Scientific achievement: Development of a reproducible HPC-based framework for comparing stochastic portfolio optimization methods.
  • Key results: Larger sampling budgets improved numerical accuracy, while optimization objectives and historical windows significantly influenced portfolio risk–return characteristics.
  • HPC contribution: HEMUS enabled repeated simulations, algorithm benchmarking and computational performance analysis.

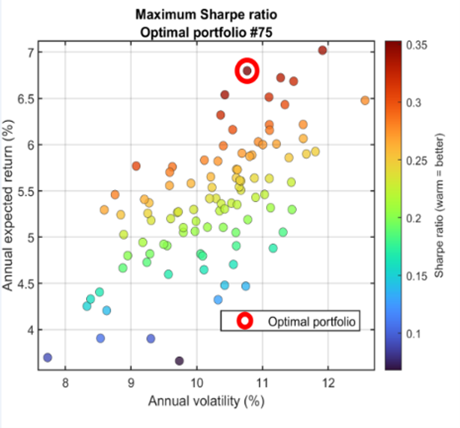
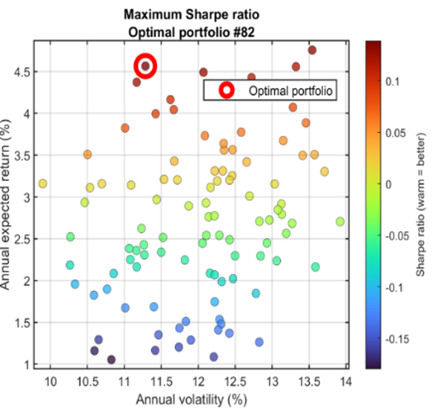
Comparison of the 3 time horizons through Sharpe-ratio optimization. Among the sampled candidates, the 5-year Sharpe solution provides the highest expected return and the strongest reward-to-risk trade-off, at the cost of the highest volatility across the three horizons

Figure 1. 3 – year hori

Figure 2. 5- year horizon

Figure 3. 10-year horizon

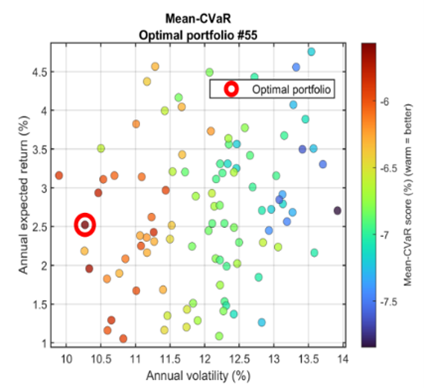
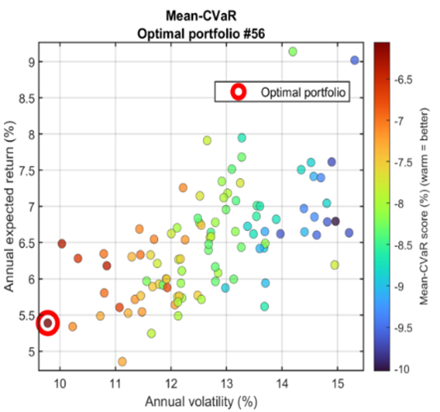
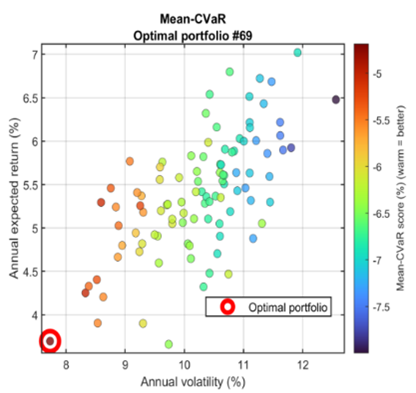
Comparison of the 3 time horizons through CVaR (5%). At N=100, Mean-CVaR shifts the selected portfolios toward lower-volatility regions. The 5-year solution achieves the highest expected return while slightly reducing volatility relative to the 3-year case, whereas the 10-year solution is the most conservative in volatility terms.

Figure 4. 3 – year hori

Figure 5. 5- year horizon

Figure 6. 10-year horizon

Figure 7. Sharpe vs CVaR: Cross-Horizon Comparison. Sharpe is higher at all three horizons. CVaR is lower at all three horizons.

Contact:

  • Silvi-Maria Gurova | IICT-BAS | silvimaria.gurova@iict.bas.bg
  • Todor Gurov | IICT-BAS | todor.gurov@iict.bas.bg
  • Aleksandar Kirilov | IICT-BAS | alex.kirilov@iict.bas.bg